

First home buyers
Deposits, grants, guarantees and pre-approval, explained in plain English. You might be closer than you think. First home buyer loans
Let's get your next move sorted.
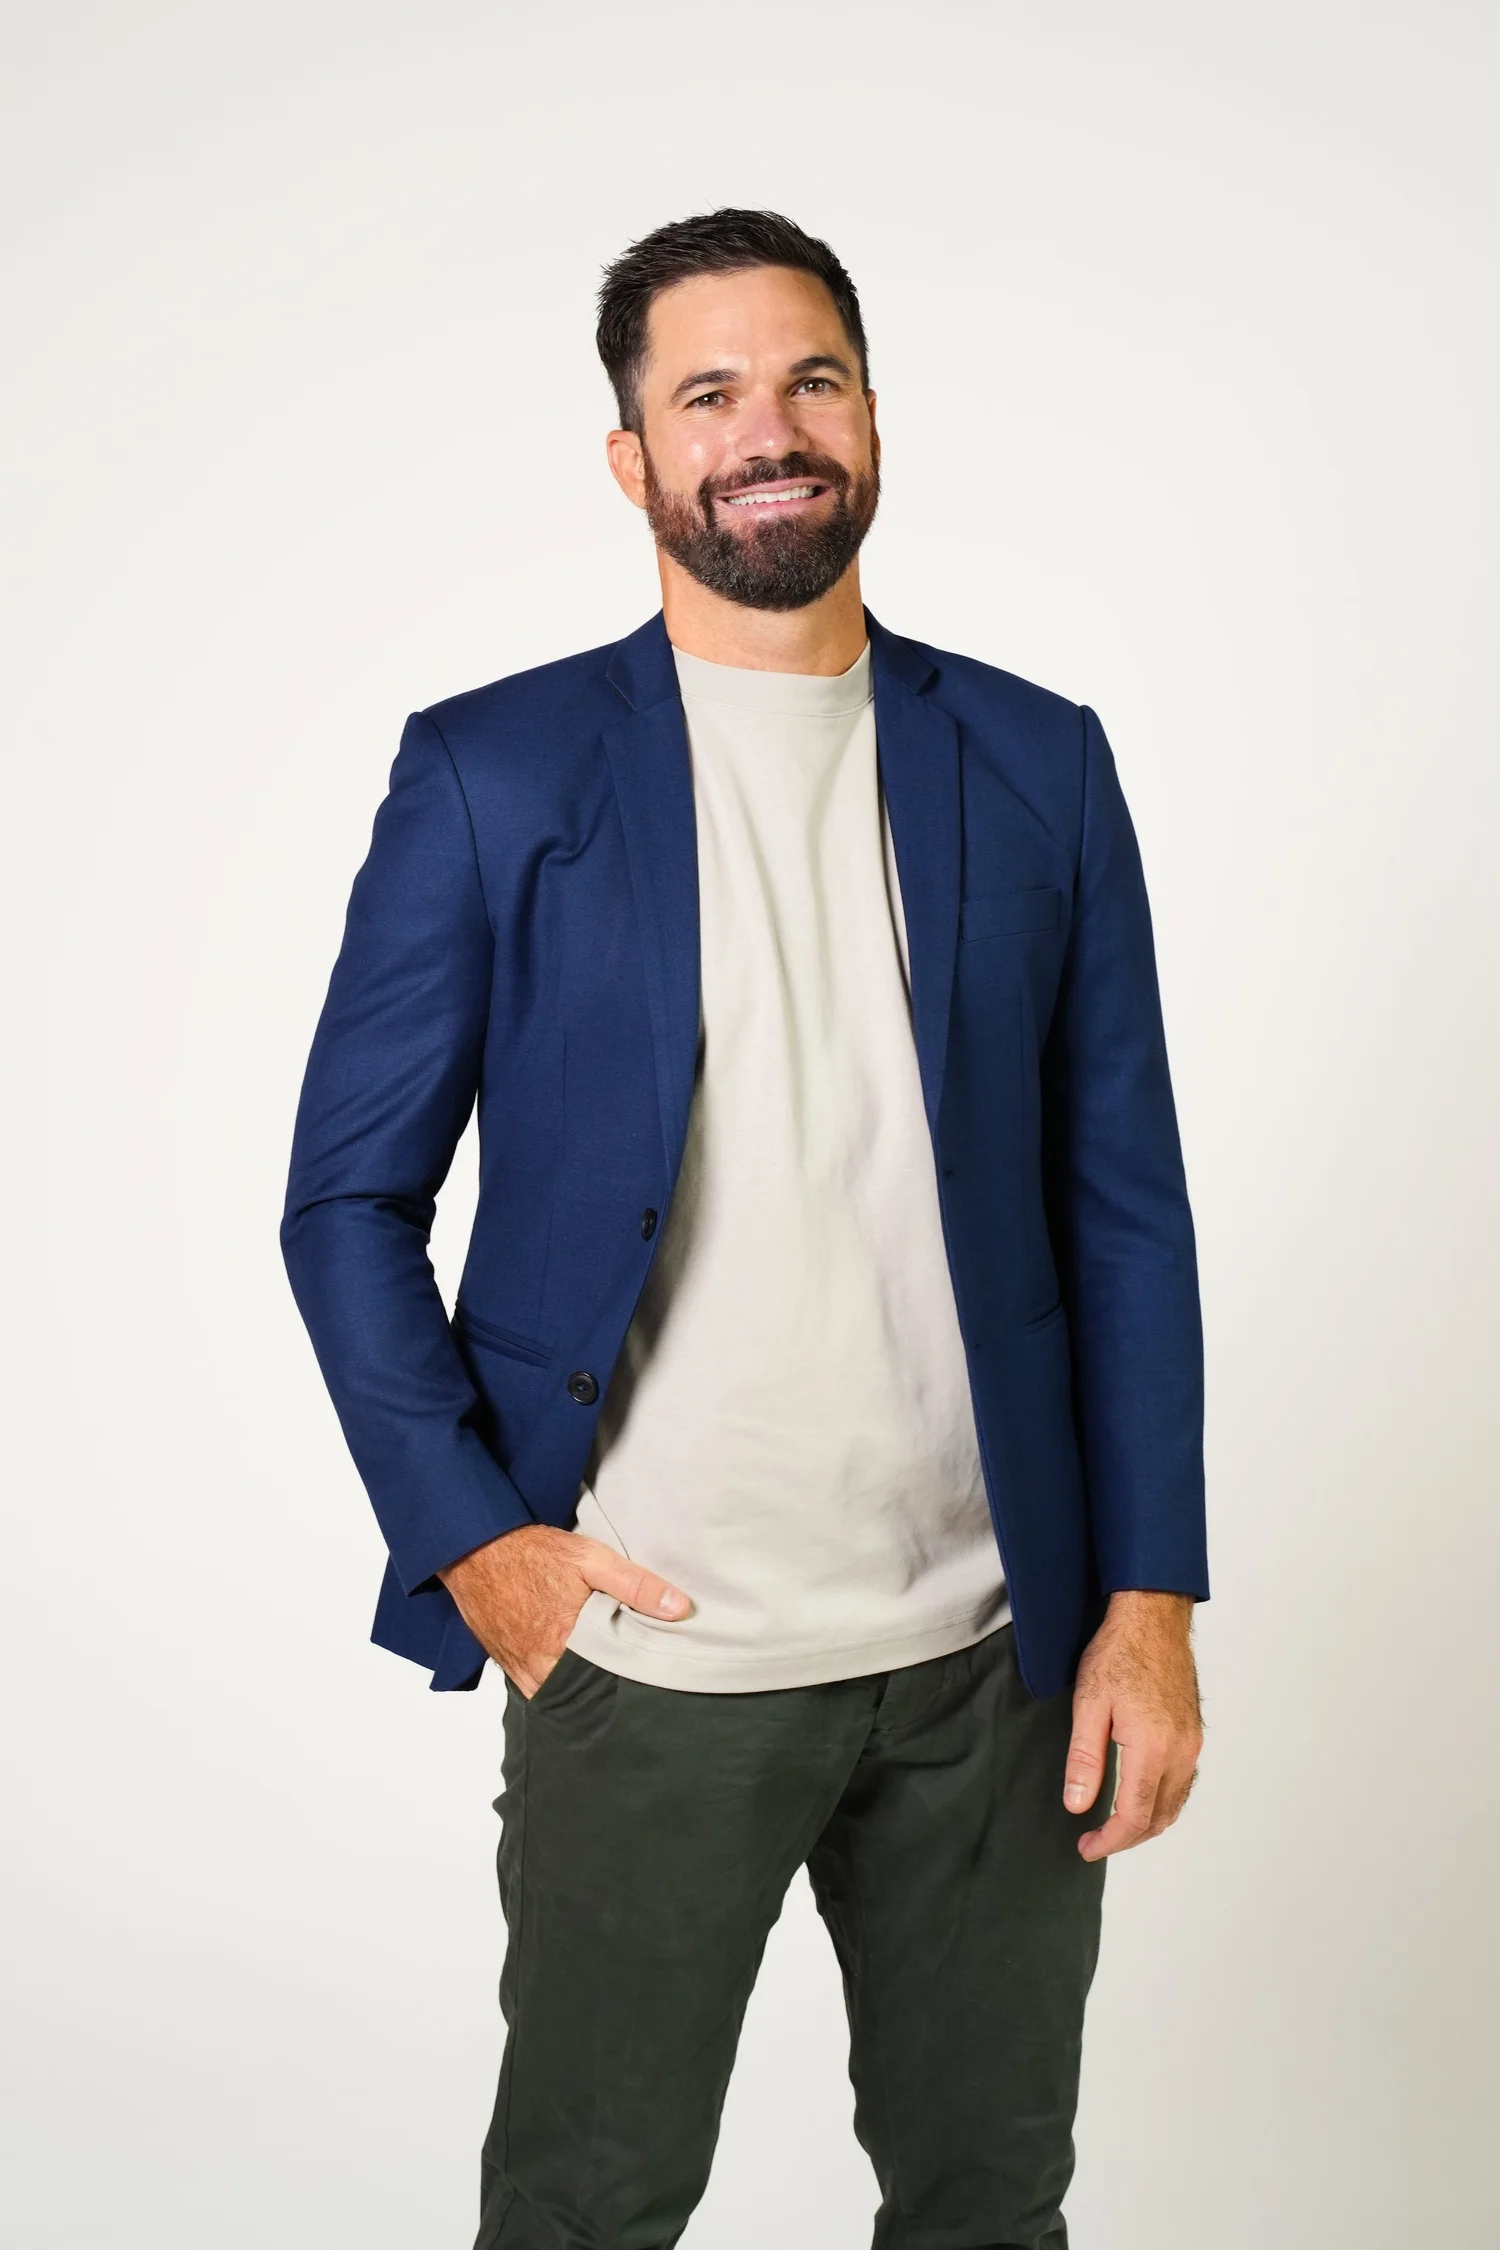
I'm Jason Birks. Whether you're buying, building, refinancing or investing, I'll find the lender that fits, out of more than 60.
5.0 on GoogleOver ten years lending at Westpac and NAB. Broker since 2025. FBAA member.
Some of the 60+ lenders I compare



With Kip the brain
A loan is one decision inside a longer plan. Before I recommend anything, I want to know what you're likely to do next, whether that's selling, upgrading, buying another property or renovating.
Then we set the lending up so those options stay open, and we talk through the risks now and a few years out.
Doing that well means knowing what lenders will actually do, and that changes all the time. I meet regularly with lenders' business development managers and read their policy updates as they come out. I also hear from the real estate agents and buyers agents I work with about what's happening in the market week to week.
Often it's a new or little-known policy that makes a deal work. There's an example just below.
I pride myself on answering quickly, whether the answer is yes or no.
Jason
The game plan
At the time, a client could see property values starting to lift and wanted to buy several investment properties before they did.
They wanted to keep their home loan where it was, because the rate was very hard to beat at the time. Their income had also gone up recently, but lenders couldn't use the new figure until the next tax return was done.
Timeline: 2025 to 2026
These clients wanted to cut the interest and costs across their home and investment loans.
Their banking was spread across three banks, they each had their own accounts sitting against joint loans, and they had an off-the-plan investment property still to settle.
Timeline: 2025 to 2026
These clients wanted to tidy up their home and investment lending, which was spread across several banks and loan types.
Each bank had suited their strategy at the time with a previous broker, but some poor experiences had left them wanting a fresh start. Next on their list was something they'd never done before: a commercial property investment.
Timeline: 2025 to 2026
Scroll to play it out
BonusA policy most people hadn't noticed at the time.
Move 1Bought with their existing bank, using a self-employed policy it had recently launched at the time, which looked at one year of income instead of two.
BonusHome loan rate left alone.
Move 2Same bank and same policy, settled soon after the first.
ChanceBackup plans ready if anything changed.
Move 3The higher income wasn't usable yet, so this one went through a low doc loan, with a plan to refinance once the tax return was in.
PaydayValues lifted, as expected.
Move 4Once the tax return was done, the low doc loan moved across to the main bank. The properties had grown quickly since purchase, so we also released equity for the client's next plans.
BonusA much sharper rate at the time.
Move 1We moved their loans to a lender offering a much sharper rate at the time and set up offset accounts, so their savings would bring the interest down further.
ChanceLife got in the way.
Move 2At their review a year later, their everyday banking had never moved across. Their savings were sitting in accounts at another bank, earning nothing and offsetting nothing.
BonusHigher rate, bigger saving.
Move 3I compared staying on the lower rate with moving the loans to the bank they actually used, so those accounts could become offsets. With balances that size, the offsets came out well ahead.
PaydayA buffer for settlement.
Move 4With the market softening at the time, we also released equity so a low valuation on the off-the-plan purchase wouldn't leave them short at settlement. Every loan was kept standalone, so they keep control if they ever sell.
BonusSharper rates across the board.
Move 1We reviewed the whole position. Property values, rents and their income had all gone up, which made a lender with much sharper rates at the time the better fit. So we moved everything across.
BonusEquity put to work.
Move 2Their next investment was a commercial property, bought through a company and built from scratch. We set aside equity from their existing properties for the deposit, costs and construction, then spent close to a year on the land, build contracts and advisers.
ChanceThe valuation came in low.
Move 3Everything hinged on the "as if complete" valuation. Their advisers expected it to come in well above the build cost. The valuer disagreed. The land had already settled, and there wasn't enough set aside to finish the build.
PaydayThe build back on track.
Move 4Their current lender's valuations wouldn't stretch any further, so I went across the panel. Borrowing capacity first, then which lenders could service it, then where valuations on properties like theirs had tended to land. The new valuations came in well higher and released enough equity to cover the shortfall.
We planned all of it months in advance, using what we knew at the time, with backup plans in case anything changed.
The lowest rate on paper isn't always the biggest saving. The right loan is the one that fits how you actually bank.
A low valuation doesn't have to end a project. Different lenders can see the same property differently, and knowing where to look is part of the job.
Details kept general so clients can't be identified. Rates, lender policies and market conditions were as they stood at the time and may have changed since. Every situation is different and lending criteria apply.

With Rover the finder
Deposits, grants, guarantees and pre-approval, explained in plain English. You might be closer than you think. First home buyer loans
Moving to your next home, including buying before you've sold. I'll walk you through bridging finance, a longer settlement or buying subject to sale, and what each would mean for you. Bridging loans
Your first investment property or the next one in a portfolio, set up with the purchase after this one in mind. I also review how existing investment loans are structured. Investment loans
If your loan hasn't been looked at in a couple of years, it's worth fifteen minutes to check it against the market. That includes releasing equity for renovations or the next purchase. Refinancing
Land and build, knockdown rebuilds and progress payments, managed so the build keeps moving. Construction loans
Self-employed, bonuses and commission, or income earned overseas. Lenders treat these very differently, and matching you to the right policy is the job. Self-employed home loans
Doctor, nurse, teacher, lawyer or accountant? Many lenders will let you borrow up to 90%, and doctors up to 95%, without paying LMI. Home loans for professionals
Buying your own premises or investing in office, retail or industrial property. Commercial property loans
Vehicles, equipment and machinery to grow the business without tying up cash flow. Asset finance
Starting, expanding or smoothing out cash flow, with lending that fits where the business is headed. Business loans
Three steps, no homework
We talk about where you are and where you want to get to. You don't need any documents for this, and there's no obligation.
I run your situation past more than 60 lenders and come back with a recommendation and my reasons for it.
I prepare the application, deal with the lender and keep you updated until the loan settles. You can save your energy for choosing paint colours.
Send an enquiry and I'll get back to you within one business day. After settlement, I check in over the first couple of months and review your loan every 12 months.
With Digits the calculator
These give you a rough idea. Lenders work out borrowing power differently from each other, so the real figure comes from running your details past them. For every state and territory, the full stamp duty calculator covers first home concessions and foreign buyer surcharges.
Estimate only. Assumes the rate stays the same for the full term and excludes fees. Not financial or credit advice.
Use gross (before tax) income. The tax is worked out for you.
Rough guide only. Lenders calculate borrowing power very differently from each other, which is exactly why comparing 60+ of them matters. Uses 2025-26 resident tax rates, a 3% assessment buffer and a 30 year term. Not financial or credit advice.
Estimate only, based on published state and territory duty rates and first home concessions as at October 2026. Government registration fees are approximate outside Queensland. Always confirm before signing anything. Not financial or credit advice.
Nice to meet you
I spent over ten years as a mobile lender with Westpac and NAB before starting Birks Financial Group in 2025, and I'm a member of the FBAA.
I grew up on Brisbane's northside and live on the southside now.
At home I have two young kids, so weekends are mostly family time, picnics and outings.
Brisbane's northside and southside, and the Sunshine Coast where most of my extended family lives, are the markets I know best. I also hear from the agents and buyers agents I work with every week about what's happening in them. You don't need to live nearby, though. Everything works over phone and video, and I have clients across Australia.
With Checkers the reviewer
Live Google reviews load here on birks.com.au.
Why two banks can give you very different numbers, and what moves yours.
A 15 minute loan health check you can run yourself before calling anyone.
Deposit, grants, pre-approval and settlement, in order.
The 20%, 10% and 5% options, plus the costs on top.
What LMI costs and the legitimate ways to avoid it.
How an offset cuts your interest, and offset versus redraw.
Weekly, fortnightly or monthly, with extra repayments and an offset.
Duty, first home concessions and foreign buyer surcharges for every state and territory.
Everything a lender will ask for, ticked off as you go.
Your equity, peak debt and loan after the sale, before you make an offer.
For almost all home loans, nothing. The lender pays me a commission when your loan settles, and I tell you exactly what it is. You'd pay the same rate going to the bank directly, but you'd only see that one bank's options.
Your bank can only offer its own products. If its policy doesn't suit your situation the answer is no, even when other lenders would say yes. I compare more than 60. Mortgage broker or bank?
It depends on the lender and the price. Many lenders want 20% to avoid lenders mortgage insurance, but there are options with less, including government schemes for eligible first home buyers. I'll tell you which ones you qualify for.
It depends on the lender and how quickly I get your documents. A few days to two weeks is typical, and I'll give you a realistic timeline up front.
No. Bridging finance, a longer settlement or buying subject to sale can each let you buy first. Which one suits depends on your equity, your income and how quickly your current home is likely to sell.
Often, yes. If your property has grown in value, you may be able to borrow against that equity for the deposit and costs on the next one. How much depends on the valuation, your income and each lender's policy, so I check all three before you start looking.
Every year or two is a good habit, and any time your situation changes or a fixed rate is about to end. For my clients I do it automatically: I review every loan 12 months after it settles to make sure it's still competitive.
Yes. Lenders treat income very differently from each other, and matching your situation to the right lender's policy is a big part of what I do.
Yes. I arrange commercial property loans, asset finance and business loans. The process is a little different from a home loan, and I'll explain what lenders will want to see before you apply.
No. Brisbane and the Sunshine Coast are the markets I know best, but everything works over phone and video, and I have clients across Australia.
If you'd like to refer a client, it takes about 30 seconds. They'll hear from me within one business day, and I'll keep you posted at each milestone.
Whether you're buying your first home, moving up, investing, refinancing or financing a business, book a 15 minute chat. You don't need any documents. If you'd rather talk now, give me a call.
My service costs you nothing. The lender pays me a commission when your loan settles, and I'll tell you exactly what it is.